Introduction
Why are business purchase prices hitting record highs at the exact moment economic uncertainty is peaking? For small business owners and prospective buyers navigating today’s M&A environment, the current market presents a glaring surface-level paradox.
On one hand, macroeconomic pressures continue to mount. Small business operators report persistent pain from stubborn inflation, surging fuel and energy expenses, and increasingly cautious consumer spending. Yet, despite these operational headwinds, high-quality small businesses are commanding higher sale prices than ever recorded.
According to the BizBuySell Q3 2026 Insight Report (supplemented by digital M&A market analyses from Flippa and FE International), the underlying mechanics of the business-for-sale market have undergone a structural shift. Overall transaction volume is slipping, but sale prices are surging. The core trend defining today’s deal environment is clear: total deal count is down, but a aggressive “flight to quality” is widening the valuation gap between documented, operationally resilient assets and sloppy, unprepared operations.
1. The Valuation Paradox: Deal Volume Dropped 7%, But Median Prices Hit $350,000
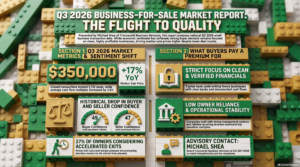
The third-quarter transaction data reveals a striking divergence between overall deal volume and final closing prices. Closed small business acquisitions fell to 2,132 deals in Q3 2026—essentially flat compared to Q2, but down 7% year-over-year. Concurrently, the median sale price rose 17% year-over-year to $350,000, while market-wide average cash flow multiples edged up 2.6%.
| Q3 2026 Transaction Metric | Metric Value / Trend | Market Context |
| Closed Transactions | 2,132 deals | Down 7% YoY; Flat vs Q2 2026 |
| Median Sale Price | $350,000 | Up 17% YoY (Record High) |
| Cash Flow Multiples | +2.6% | Upward directional expansion |
Analyst Note on Baseline Data: A closer examination of historical reporting reveals an important analytical nuance. BizBuySell’s original Q3 2025 report cited 2,599 closed deals and a 320,044 median price. The 7% volume drop and 17% price increase reported for Q3 2026 reflect an internal baseline restatement by BizBuySell to roughly ~2,290 deals and ~299,000 median price for the prior-year period. Furthermore, BizBuySell does not explicitly define the baseline period for the +2.6% cash flow multiple shift; thus, dealmakers should interpret this metric as an indicator of directional multiple expansion rather than a precise point-to-point calculation.
This valuation growth does not signal a tide lifting all boats. Instead, total deal volume is shrinking because buyers are actively rejecting underperforming, messy, or high-risk businesses. When sloppy or poorly documented assets fail to reach the closing table, they drop out of the transaction sample entirely.
Consequently, the median price is pulled upward because only top-quartile, highly profitable companies are finalizing transactions. Sellers cannot simply list an unprepared business and expect a 17% price premium; the rising median reflects an uncompromising market where only clean assets are clearing buyer scrutiny.
2. Confidence Sinks: Buyer and Seller Sentiment Suffers Historic Double-Decline
Despite record-high closing prices, market sentiment across the M&A landscape has cracked a 13-year historical floor. BizBuySell’s tracking indicates that buyer confidence fell to 49, while seller confidence dropped to 47.
Crucially, both buyer and seller confidence have now declined year-over-year for two consecutive years. This synchronized double-decline marks an unprecedented multi-year drop since BizBuySell began tracking sentiment metrics in 2013.
| Sentiment Benchmark (Q3 2026) | Index Score | Historical Context |
| Buyer Confidence Index | 49 | 2nd consecutive year-over-year decline |
| Seller Confidence Index | 47 | 2nd consecutive year-over-year decline |
| Historical Significance | Historic Low | First back-to-back double-decline since 2013 inception |
Deteriorating seller sentiment is directly tied to compounding margin compression and operational fatigue:
- 75% of business owners report elevated fuel and energy expenses. This is corroborated by the TD Cowen-AFS Freight Index, which logged fuel surcharges up 79% year-over-year in September.
- 67% of sellers report that inflation is not easing.
- Over 50% of owners observe increasingly cautious spending behavior across their customer bases.
This ongoing margin squeeze is inducing severe seller fatigue. As a result, 27% of prospective sellers state that current economic pressures have forced them to consider exiting their businesses sooner than originally planned.
3. The Flight to Quality: Why “Preparation Is the Multiple Now”
While market confidence has softened, acquisition capital remains abundant. Buyer interest has not vanished—Flippa reported 123,022 active buyers in H1 2026, an 18% increase year-over-year—but buyers are exercising strict discipline. Capital is concentrating heavily into businesses that demonstrate verifiable cash flow, limited owner dependence, and pristine financial reporting.
As Bob House, President of BizBuySell, noted regarding the market dynamic:
“Confidence has softened, but buyers haven’t left the market. They’re simply becoming more selective. Buyers are gravitating toward businesses with reliable cash flow, clean financials, limited owner dependence, and a clear path to financing. Those qualities can make the difference between attracting interest and attracting serious offers.”
This shift toward extreme capital discipline is mirrored across institutional and digital M&A markets. In the Amazon aggregator market, for example, institutional players have consolidated from over 100 active entities down to just 57, with average multiples compressing from peak levels of 6x–7x EBITDA down to 3x–4x EBITDA. Across digital and Main Street transactions, deal structures have adjusted accordingly: upfront cash now typically represents 60% to 75% of the purchase price, with the balance structured via earnouts extending across 12 to 24 months.
As Sebastien Stanley-Jones, EMEA Regional Director at Flippa, observed: “Preparation is the multiple now.”
The financial premium placed on preparation is quantifiable in market valuations:
- Average vs. Top-Quartile Multiples: In the ecommerce sector, Flippa data shows an average earnings profit multiple of 1.55x, whereas top-quartile, audit-ready businesses achieve 2.75x.
- The Valuation Gap: On a business generating $400,000 in annual Seller’s Discretionary Earnings (SDE), the valuation gap between an average listing (1.55x = $620,000) and a top-quartile prepared business (2.75x = 1,100,000) represents a **480,000 spread** driven almost entirely by operational and financial preparation.
4. Regulatory Squeeze: New SBA Financing Rules Raise the Bar for Borrowers
Underpinning this buyer selectivity is a tighter debt environment. On September 16, the Federal Reserve raised its target rate range to 3.75%–4.00%, driving up interest costs for leveraged acquisitions. Compounding this, the Small Business Administration (SBA) implemented revised standard operating procedures (SOP 50 10 8.1), effective October 1, which significantly tighten credit requirements for SBA 7(a) acquisition debt.
Key regulatory changes directly impacting deal execution include:
- Increased Debt-Service Coverage Ratio (DSCR): The minimum required DSCR for most change-of-ownership transactions was raised from 1.15x to 1.25x.
- Mandatory Quality of Earnings (QofE): Independent QofE reports are now mandatory for transactions with purchase prices of $3 million or higher.
| SBA SOP 50 10 8.1 Rule Update | Previous Requirement | New Requirement (Effective Oct 1) |
| Debt-Service Coverage Ratio (DSCR) | 1.15x Coverage | 1.25x Coverage |
| Quality of Earnings (QofE) Mandate | Lender Discretion | Mandatory for Deals $3M+ |
From an M&A underwriting perspective, lenders are requiring mandatory QofE reports at the $3 million threshold to scrub earnings, verify quality of revenue, and eliminate unverified owner add-backs before committing capital.
The Debt Service Math: The shift from a 1.15x to a 1.25x DSCR requires a business to generate significantly higher documented earnings to support the same loan amount. For example, if a buyer’s annual debt service on an SBA acquisition loan is $150,000:
- Under the old 1.15x threshold, the business needed to demonstrate $172,500 in historical SDE.
- Under the new 1.25x threshold, that same loan requires 187,500** in verified SDE—a **15,000 annual earnings increase required to finance the exact same debt load.
If a seller’s books rely on aggressive, unverified add-backs or sloppy accounting, SBA-financed buyers will be priced out or rejected during underwriting.
5. The Danger of the Rushed Exit: Avoiding the Hidden “Value Slashers”
With 27% of small business owners considering an accelerated exit due to economic strain, many risk making costly concessions. In an environment where buyers face higher borrowing costs and no pressure to overpay, hasty listings face steep price cuts or risk failing in due diligence.
When buyers, brokers, and lenders inspect a target business, specific operational weaknesses—known in M&A as “Value Slashers”—will instantly erode purchase price or collapse transaction terms:
- Disorganized Books and Unverified Add-Backs: Financial records that do not reconcile directly with bank statements and tax filings destroy deal credibility. Unverified owner add-backs are routinely rejected by lenders during credit review.
- Heavy Owner Dependence: A lack of standardized operating procedures (SOPs) or capable middle management indicates that operational value rests in the departing founder, creating immense post-closing risk.
- Supplier Concentration Risk: Over-reliance on a single vendor—specifically where any single supplier accounts for more than 40% of inventory or total revenue—presents a supply-chain vulnerability that buyers discount heavily.
- Unaddressed Sales Tax and Legal Liabilities: Outstanding sales tax exposure (such as 24-month lookback liabilities for remote and digital sellers under state nexus laws) or unfiled corporate governance documents can force buyers to walk away or demand restrictive indemnity escrows.
In today’s selective market, a thin or unorganized listing file will not merely fetch a lower price—it will sit on the market for months, stall in diligence, get relisted, and carry a permanent buyer stigma that destroys enterprise value.
Conclusion & Final Takeaway
The Q3 acquisition market sends a clear message to business founders and investors: demand for quality assets remains intact, but the era of easy exits for unorganized operations is over. Today’s acquisition environment heavily rewards rigorous financial documentation, operational transferability, and clean unit economics, while penalizing operational shortcuts.
For business owners planning an exit over the next 12 to 36 months, maximizing exit value depends on internal audit-readiness rather than attempting to time macroeconomic cycles.
A Final Thought for Business Owners: If a selective buyer walked into your business today and demanded 24 months of pristine, audit-ready financials—would you command a top-quartile multiple, or would you be forced to leave hundreds of thousands of dollars on the table?
Michael Shea represents the Tampa Florida Transworld office. In business since 2005, he has established a reputation as a trusted business broker across Florida’s key markets- from Tampa to Orlando, Melbourne, and more. Over the past two decades, Michael and his team have closed over $1 Billion in sold business volume and presided over more than 480 transactions. His credentials include the IBBA Certified Business Intermediary®, and most recently, the prestigious Certified Exit Planning Advisor® (CEPA) credential. He is also a Florida Licensed Real Estate Broker and Business Brokers of Florida Board Certified Intermediary . Shea is a member of the VRMA and a recognized expert in property management and vacation rental management business sales