By Michael Shea, Transworld Business Advisors
If you own a roofing company in Tampa Bay, Clearwater, St. Petersburg, Orlando, or elsewhere in Florida, you may have wondered: What is my roofing business actually worth?
It is a fair question. You may have spent 15 or 20 years building a reputation, developing relationships with homeowners and contractors, hiring crews, managing insurance claims, and navigating Florida’s demanding roofing market.
But here is the important point: the value of your roofing company is not determined by revenue alone. It is determined by sustainable earnings, the quality of those earnings, and what a qualified buyer can reasonably expect to earn after taking over the business.
A roofing company generating $5 million in annual sales is not automatically worth more than one generating $3 million. If the first company has inconsistent margins, depends entirely on its owner, and relies on unpredictable storm-related work, the smaller company could be the more attractive acquisition.
As a business broker with Transworld Business Advisors, I encourage owners to look beyond the top-line number and understand what a buyer is really purchasing.
Here are nine factors that can make a significant difference when valuing a roofing business.
1. Start With Profit, Not Revenue
Revenue tells you how much roofing work you sell. Profit tells you how much money the business actually generates.
Buyers want to understand the earnings available to them after accounting for the real cost of operating the company.
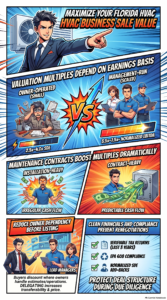
For smaller, owner-operated roofing businesses, the starting point is often Seller’s Discretionary Earnings (SDE). For larger companies with professional management, the analysis may focus on EBITDA, or earnings before interest, taxes, depreciation, and amortization.
Consider this simplified example:
| Financial measure | Roofing Company A | Roofing Company B |
|---|---|---|
| Annual revenue | $5,000,000 | $3,500,000 |
| Normalized earnings | $350,000 | $525,000 |
| Earnings margin | 7% | 15% |
Company A has more revenue. Company B generates substantially more earnings from every dollar of sales.
All else being equal, a buyer may prefer Company B because it has stronger profitability. The final valuation would still depend on the type of earnings being measured, the company’s risk profile, its size, and the buyer’s objectives.
The lesson: Before worrying about a multiple, establish how much money your roofing company consistently makes.
For more information, read Michael Shea’s guide to how to price a business for sale and attract the right buyers.
2. Understand the Difference Between SDE and EBITDA
Not every roofing company should be valued using the same earnings metric.
SDE: The owner-operated roofing company
SDE is commonly used for smaller businesses where a buyer expects to take an active role in operations.
It generally starts with business earnings and adds back items such as the owner’s compensation, interest, taxes, depreciation, amortization, and legitimate discretionary or nonrecurring expenses, subject to appropriate adjustments.
However, an add-back is not automatically acceptable just because the seller identifies it.
If you pay yourself $180,000 and a buyer must hire a qualified general manager to replace your responsibilities, the buyer needs to account for that replacement cost when determining the economics of the acquisition.
EBITDA: The larger, professionally managed roofing company
EBITDA is often more useful when a business has a management team and can operate without its owner performing a full-time operating role.
It is particularly relevant when evaluating larger strategic acquisitions or potential private equity transactions.
The distinction matters because buyers are not all purchasing the same thing.
An individual buying a roofing company to create a job has different financial considerations from a regional roofing contractor acquiring a competitor or an investment group building a larger platform.
The right valuation method depends partly on who your likely buyer will be.
3. Apply the Right Multiple—Not the One You Found Online
Once normalized earnings have been established, a valuation may apply an earnings multiple.
Roofing business valuation articles commonly cite broad illustrative ranges around 2.5–4 times SDE for smaller owner-operated companies and roughly 3.5–6 times EBITDA for some established larger businesses. These are general reference points, not verified offers for your company or guaranteed transaction results. Actual multiples can fall outside these ranges.
Here is how the math works.
Suppose a roofing company generates $400,000 in normalized SDE.
| Illustrative multiple | Indicated value |
|---|---|
| 2.5× SDE | $1,000,000 |
| 3.0× SDE | $1,200,000 |
| 3.5× SDE | $1,400,000 |
| 4.0× SDE | $1,600,000 |
These figures demonstrate the effect of a multiple. They do not establish what a particular company would sell for.
Notice that a difference of just one turn in the multiple changes the indicated value by $400,000.
That is why valuation is more than plugging numbers into a calculator. You need to understand which comparable transactions are relevant, how earnings have been calculated, and why a buyer would pay a higher or lower multiple.
For a broader discussion of valuation, visit Michael Shea’s free business valuation resource.
4. Determine Whether Your Revenue Is Predictable or Weather-Dependent
This is particularly important in Florida.
Roofing companies may generate revenue through several channels:
- Residential roof replacements.
- Storm damage and insurance-related projects.
- Commercial roofing.
- New construction.
- Roof repairs and maintenance.
- Recurring commercial service agreements.
- Property management and contractor relationships.
These revenue sources do not carry identical risk.
A company that experiences an exceptional year after a major storm may report impressive sales and earnings. But a buyer will want to know whether those results are repeatable.
What happens when storm activity declines? Are leads generated consistently? Does the business have an established referral network? Can the company maintain its margins during slower periods?
Commercial maintenance agreements and repeat customer relationships can help make revenue more predictable. However, buyers will examine the actual contract terms, renewal history, margins, and customer retention rather than simply accepting the label of recurring revenue.
A buyer is purchasing future earning potential, not just last year’s storm season.
5. Evaluate How Dependent the Company Is on You
This may be one of the biggest differences between a roofing company that is easy to transfer and one that is difficult to sell.
Ask yourself:
- Do you personally estimate most jobs?
- Are you the primary salesperson?
- Do customers insist on dealing directly with you?
- Do you resolve nearly every production problem?
- Do you control all subcontractor relationships?
- Would the business struggle if you took a month off?
If the answer to most of these questions is yes, you may have built a successful business—but you may also have created a job that is difficult to transfer.
Buyers pay for systems, relationships, and earnings that can continue after the current owner leaves.
A company with a capable production manager, documented estimating procedures, reliable crews, and an established sales process may be more attractive than a similarly profitable business that depends on the owner for every important decision.
The goal is not necessarily to eliminate the owner. It is to demonstrate that the business can continue operating successfully under new ownership.
6. Examine Your Crews, Subcontractors, and Management Team
Roofing is a people-intensive business. Your ability to complete jobs safely, on schedule, and at the expected margin is central to your value.
A buyer will want to understand:
- Whether crews are employees or subcontractors.
- How subcontractor relationships are documented.
- Whether key supervisors are likely to stay.
- How quality control and callbacks are managed.
- Whether workers’ compensation, insurance, and safety practices are appropriately maintained.
- Whether the company can take on additional work without sacrificing quality.
A company that sells a great deal of work but struggles to install it profitably has a different risk profile from one with disciplined production management.
Documentation matters, too. A buyer needs confidence that important relationships and operating procedures can survive the transition.
Before a sale, roofing owners should review key personnel, subcontractor agreements, insurance coverage, safety documentation, and any legal or licensing requirements applicable to the business and its proposed new owner.
7. Look at Your Customer Mix and Backlog
Not all sales pipelines are equally valuable.
A roofing company with hundreds of customers, a strong referral network, and a diversified mix of residential and commercial work may be less vulnerable than one relying on a small number of large accounts.
Buyers will often examine:
- Customer concentration.
- Referral sources and lead-generation costs.
- Historical close rates.
- The percentage of repeat customers.
- Signed contracts and committed backlog.
- Cancellation rights and project completion obligations.
- Warranty claims, callbacks, and outstanding disputes.
Backlog deserves particular attention.
A signed contract does not necessarily represent profit. The buyer must consider the remaining cost to complete the work, material pricing, labor availability, customer cancellation provisions, deposits received, and any potential warranty exposure.
A large backlog can support a valuation when it is profitable and realistically executable. It can also create risk if the company has accepted jobs at margins that are no longer achievable.
The objective is to show buyers not just how much work you have sold, but how much profit that work is expected to produce.
8. Review Equipment, Vehicles, Working Capital, and Debt
Roofing companies may own trucks, trailers, lifts, tools, inventory, and other operating assets.
These assets matter, but there is an important distinction between owning equipment and owning a profitable business.
A buyer will evaluate the condition, usefulness, and market value of equipment, along with the cost of replacing aging vehicles or tools. Equipment already required to generate the company’s earnings should not automatically be counted twice by adding its full value on top of an earnings-based valuation.
The transaction structure matters as well.
For example, the parties may need to agree on:
- Which assets are included in the sale.
- Whether inventory is included or separately counted.
- How accounts receivable and accounts payable will be handled.
- Whether a normal level of working capital must be delivered at closing.
- How debt, equipment loans, and liens will be treated.
- Whether real estate is included or leased separately.
A company can have an attractive headline valuation and still leave the seller with a different amount of cash at closing than expected.
That is why business value, transaction structure, debt, working capital, and net proceeds should be evaluated separately.
9. Prepare the Business Before You Put It on the Market
One of the most useful things a roofing owner can do is begin preparing before deciding to sell.
You do not need to be ready to retire next month to benefit from understanding your company’s value.
Start with these steps:
- Clean up the financials. Make sure tax returns, profit-and-loss statements, balance sheets, and job-costing reports tell a consistent story.
- Document legitimate add-backs. Keep supporting records for owner expenses and nonrecurring costs rather than relying on verbal explanations.
- Track job-level profitability. Understand margins by job type, crew, customer, or revenue channel where practical.
- Reduce owner dependence. Delegate estimating, production oversight, and customer management where possible.
- Strengthen recurring relationships. Develop service and maintenance opportunities where they make economic sense.
- Organize contracts and compliance records. Review licensing, insurance, warranties, employee records, subcontractor agreements, and customer commitments.
- Build a realistic forecast. Show how the company is performing now, what work is already committed, and what assumptions support future growth.
These steps can help you operate more effectively today while making the business easier for a prospective buyer to understand tomorrow.
For additional guidance, see Michael Shea’s article, What Is My Tampa Business Worth? Seven Things Buyers Look At.
What Is Your Roofing Business Really Worth?
There is no single formula that accurately values every roofing company.
Two businesses can have similar revenue and earnings but attract different offers because of differences in management, customer concentration, recurring work, licensing, profitability, and the amount of risk a buyer must assume.
The most useful starting point is to determine your normalized earnings, identify the likely buyer pool, evaluate relevant market evidence, and understand how the transaction would be structured.
For roofing business owners in Tampa Bay, Clearwater, St. Petersburg, Orlando, and throughout Central Florida, Michael Shea of Transworld Business Advisors can help you evaluate these questions as part of a confidential business valuation and sale-planning process.
You do not have to be ready to sell to benefit from knowing what your business is worth. Understanding the value drivers today gives you time to improve the business before you decide to exit.
Take the Next Step
- Request a free, confidential business valuation.
- Learn more about Michael Shea and Transworld Business Advisors.
- Visit YourFloridaBusinessBroker.com for additional business valuation, exit planning, and selling resources.
Michael Shea is a business broker with Transworld Business Advisors serving business owners in Tampa Bay and throughout Central Florida. A preliminary valuation is an estimate based on available information and market evidence; it is not a guarantee of the price a buyer will pay. Final transaction value depends on the specific business, buyer, financing, due diligence, and negotiated terms.